Saturday, April 30, 2011

How is the Qantas frequent flyer program like an angry Russian Model

After ten years I have lost platinum status with Qantas. I fell about 8% short of the status credit target so find myself in the unexpected position of carrying a gold rather than platinum frequent flyer card on my many travels. Time away from the black card has allowed me to reflect on what I am missing and the value of platinum membership. I have decided that losing platinum status is like breaking up with a gorgeous but temperamental eastern European super model. They looked beautiful, your friends were impressed and the promise for excitement was high. But in reality you were treated really badly, the private times never matched the public promise and all that sticks in your mind long after the relationship is over is how often you fought over the stupid things they did but refused to apologize for.

So farewell Qantas Platinum/Ivanka. In my dark moments I miss you and wish I was still part of in crowd that gravitated around you. But without you my life has less missed expectations and fights on the side of the curb....my friends say I am better off.

Thanks to teelwan via flickr for the photo

Monday, April 25, 2011

5 of the Best from the Shearwater Blog

Congratulations to blogger and travel/payment executive Martin Collings. For six year Martin was an executive at Amadeus in Europe and Chicago. For two and a half year Martin blogged on online travel and ancillary sales via his Shearwater press site (also a Tnooz node). This week I learned that Martin had moved back to Australia to take up a position as VP Market Development for Mastercard. Martin is pausing his writing at the Shearwater blog. But I thought I should share with you some of his best posts.

  1. "Using a Bow Tie to Make Optimal Marketing and Technology Investments": great piece fro 2009 on ancillary revenues and the inspiration funnel;
  2. His five part series on Tnooz on travel inspiration including the Inspiration Footprint Matrix;
  3. "Google Travel delivers best piece of market research I've seen in the past year": distilling some great insight into the Euro/UK online travel market;
  4. His irreverent take on innovation and travel in "Awards from PhoCusWright that you may not want to win" ; and
  5. Great piece on Hipmunk on Tnooz where he manages to get a reference to Fortitude Valley Brisbane into the same sentence as Silicon Valley
Many more over at the Shearwater blog.

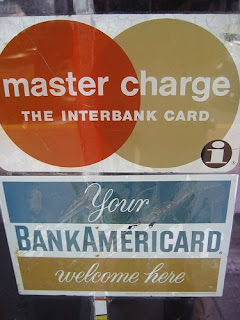
Thanks to Bill on Capitol Hill for this fantastic photo of the old mastercard and visa branding

Sunday, April 24, 2011

Indian online travel players hit accelerator....again!

The Indian online travel industry seems (in market designed to produce mixed metaphors) to burst in waves. Back in 2008- the four leading companies of India - Makemytrip, Cleartrip, Yatra and Travelguru seemed to have created a $2bb plus online travel market from a near standing start.

In their recent India report, PhoCusWright now puts the 2010 online travel market (leisure and un-managed business) at more than double 2008. $4.3bb is their size estimate, as much as 25% of the total travel market. They predict a rise to $7bb in 2012 (you can buy the report here). That would put the India of 2012 at the same size as the online market of Australia in 2010. An almost unrivaled acceleration in online travel. Like many markets online, the buying of low cost carrier tickets is a huge driver. But, unlike many markets, rail is a significant part of the grow story in India. Online rail in India is already more than a $1bb a year and is more than a quarter of the online travel industry's total turnover. In India (according to PhoCusWright), the percentage of rail online is twice the percentage of hotel online.

Corporate activity is accelerating alongside the market acceleration.

Number one player MakeMyTrip (MMYT) has been public for less than a year (IPO in August 2010). They went to the market at $14 and are still trading above $30 (Apr 21 at $32.23) with a valuation in excess of $1.1bb.

Cleartrip is chasing hard. They have just raised $40 mm from travel travel expense and management solution provider Concur (you remember them, they bought TripIt in Feb for up to $120mm).

Not to be left out, a day later Yatra announced they were raising $45mm from raised from Valiant Capital Management, Norwest Venture Partners, Intel Capital and others (WSJ story here). According to the WSJ this eclipes the $33.8mm they raised in the last round. The article quotes sources saying that a float in the next 12-18 months is very likely.

Expedia is also refusing to be left out. They have added India to their list of markets covered by their JV announced with Asian low cost carrier giant Air Asia.

Via is trying to argue there is room for more players. With $15mm raised so fare from NEA Indo-US Ventures, Sequoia Capital India and others, Via (also known as Flightraja) has mega bucks in their sites announcing last month they intend (emphasis on intend) to raise another $100mm.

Travelocity are trying to peek their head above the noise through a marketing relationship with Mastercard.

A very busy 30 days in a fast growing market. Did I miss anything? For the Tnooz latest list of top travel sites in India care of Hitwise click here.

Thanks to FriskoDude for the great photo via flickr

Thursday, April 07, 2011

Search, Social and Mobile- pre Eyefortravel thoughts via eHotelier


I am speaking this year at Eyefortravel May 18-19 in Singapore

I have put together some pre-conference predictions for 2011 (based on by full 2011 predictions). They were picked up and published in a post on eHotelier along side predictions from Robert Bailey of Abacus and (Professor) Timothy O'Neil-Dunne of LUTE technologies (and so much more). Check out the full text here.

My predictions are:

  • Search changes (again); Search already changed forever in 2010. There is more to come in 2011, especially in the measure of authority. The old measure of inbound links will be enhanced with input from social networks, context and location, expert advice, preference matching and more. Search marketing will have to change to encompass content, social, information syndication and data mining. All suppliers and all OTAs will need to ensure that their SEO experts and agents are on top of this change. In addition to the changes in authority, search will change in how results are displayed;
  • Social media will challenge search and retail: the parallel rises of social media, customers asking more complicated (and open) questions online and consumers willingness to discuss and share everything openly and freely will drive through 2011 a change the way the industry attracts and retains customers. The traffic numbers of Facebook, Twitter, foursquare etc are all but unprecedented. But it is not their rise that is the story. The story is the consumer behaviour behind the rise of these products. Pick your metaphor - consumers have opened the kimono, dropped their pants or invited everyone in to their lives. Nothing is sacred. Everything can and will be shared. Marketing channels will need to be adjusted. Communications techniques changed. Customer care models and response times adjusted. Even sales channels will need to be reworked. Get ready for social search, book and buy; and
  • Mobile becomes a distinction without meaning: iPhone did for the smart phones what diet coke did for soda. It created a category, lifted other categories with it and made people buy more of everything around it. The consequence is that people are using their phones (and now tablets) while they are on the move and as a replacement for laptops. Mobile no longer means mobile. By that I mean people will sit in meetings, on couches as home, at the desk...anywhere...everywhere...expecting to be connected. Not caring if a device is called a phone, tablet or netbook. Just caring that it gets them the content or experience they want. The result is device platform discussions will move from "which product is this built for" to "is this compatible for all displays". Much like we now say that a site has to be web ready rather than differentiating between its readiness on FireFox, Chrome, Safari, opera and IE. The type of the device and whether or not it is mobile is now irrelevant. Mobile/PC/Tablet will be the different "browsers" of 2011. All code will need to be written in preparation for this.
For a reminder of my thoughts on last year's Eyefortravel check out this post.

Tnooz: HomeAway, Home and Away and the links between online travel and teen angst

HomeAway is the largest vacation rental site in the world. Home and Away is one of Australia's longest running soap operas and a launch pad for plastic surgeons, vampire hunters and psychotic clowns. What do they have in common? Check out my latest Tnooz post "HomeAway and the real life Home and Away soap opera" to find out.

Wednesday, March 30, 2011

Social media is either overhyped, underhyped, or somewhere in the middle

Across two conferences two sets of travel executives have highlighted the challenges in figuring out how much to invest in social media for online travel companies. At last year's PhoCusWright Steve Hafner of Kayak called social media "overhyped". A session or two later former Expedia CEO Rich Barton called it "underhyped". At this year's No Vacancy Glenn Fogel of Priceline called social media experts "charlatans" while Toga Hospitality CEO Rachel Argaman said the future of the internet was pages inside Facebook. Meanwhile Wotif provided the perfect case study to test this debate by launching $11 rooms for 11 minutes via social media.

In my latest Tnooz post I discuss this debate and look in depth at the Wotif promotion. Check out the story here.

Tuesday, March 22, 2011

No Vacancy tomorrow - follow #novac11 for updates

The BOOT will be at the No Vacancy conference tomorrow in Sydney. Come find me at the event or follow all the live tweeting live from @hughestim and #novac11.

PS = #novac is the tracking for Novac Djokovic.

Monday, March 21, 2011

Jetsetter reports 176,000 room nights since launch

We know that the flash and private sale models are working well and growing fast. But how well and how fast? In an article from SF Gate Jetsetter CEO Drew Patterson spills some interesting performance metrics on the company (and by implication the sector). Highlights from the interview include:
  • Member number: 2 million members. Two thirds from parent company Gilt group. One third acquired independently;
  • Turnover: 176,000 room nights since launch "via 800 partners in over 70 countries". That's the quote from the interview. Let's try a bit of back of the envelope maths and see what this means for the overall size of the business. Jetsetter launched in Sept 2009 so that is 176000 room nights in eighteen months of operation. Let's guess an average daily rate well above industry average of $250. That is $44 million in gross bookings for Jetsetter over 18 months. If you guess that the second year is 100% bigger than the first then that puts year 1 gross booking at $22mm and year 2 on track for $40-50 million in gross bookings.
  • Customer care: they have a team of 12 in-house to answer customer and supplier emails. Is committed to answering all emails in 2 hours (something Patterson says he learnt from working at Kayak)
  • International expansion: Currently 10% of customers outside the US
Read the full story here

Thanks to JPhilipson via flickr for the great flash kid photo

Thursday, March 10, 2011

CustomerUnderground is mad as hell and low cost carriers are to blame

Home
Over at the CustomerUnderground I posted a 5,500 word rant about my living, loving and hating Dell. CustomerUnderground co-founder "Higherthanexpectedcallvolumes" has posted a piece that might interest you. He has put up an old school customer I've-had-enough-a-thon about the low cost carrier business. The trigger the story of a nurse who tried to help another passenger on a Jetstar flight. As a result she missed her return journey and Jetstar tried to charge her to rebook her flight.

Check out the rant here - it is called "Why do Low Cost Airlines Hate their Passengers (and What Do We Do About it)?"

Wednesday, March 09, 2011

BOOT will be at No Vacancy in Sydney March 23

The BOOT will be joining hundreds at the No Vacancy Conference in Sydney on March 23 (Dockside, Darling Harbour).

Speakers I am looking forward to include:
UPDATE - note after the Fairfax and Occupancy deal, Justin and Kirsty will be replaced David Anderson (MD Transaction Division of Fairfax Division)

Full list of speakers here.

Tickets still available here. 200 have already signed up to join (list of attendees as at March 7 here). Let me know if you are going to be there.

Tuesday, March 08, 2011

Fairfax buys Occupancy.com - owns online vacation rental market in Australia

News out this morning that vacation rental and short let group Occupancy.com has been bought by media company Fairfax. Occupancy will now be combined with Stayz.com to form the clear and unambiguous number one in the vacation rental/short let online market in Australia. According to the SMH the sale was for $29.1mm. The Australian says this is made up of $17.9mm in cash and $11.2mm in shares in the combined entity. The shareholders of Occupancy will retain 10% of the shares in the combined group. Does this mean the combined entity is valued at $112mm??? (will need to investigate).

Sites in the combined group will include Stayz, Rentahome and Takeabreak. Early news is that it will be combined with the NZ businesses for Fairfax holidayhomes.co.nz and Bookit.co.nz. Not sure what it means for Travelbug.

This is a big move.The Combined Stayz and Occupancy likely have 60-66% of the market for online vacation rental and short lets in Australia. With Yahoo7's TotalTravel second and Realholidays (subsidiary of Real Estate.com.au) a very distant third.

I will do more analysis later - hopefully including an interview with someone at Occupancy. For background:
Still to find out:
  • Who will do what in the new company? Note Kirsty Shaw used to be the GM of Stayz. Now her Linkedin profile says Director Strategy and operations - Transactions Division at Fairfax Digital (though the linkedin dates say this change has been in place for more than a year);
  • What will happen to each of the three brands?;
  • Where does this fit with other travel assets like Travelbug in Nz; and
  • Will the 10% ownership by founders of Occupany and the restructure at Fairfax itself mean anything in terms of the massive cross promotion that Stayz gets from Fairfax sites?

Monday, March 07, 2011

An insurance salesman selling hope while entertaining via TEDx

WorldNomads General Manager Chris Noble is one of my favourite conference beer buddies. I have enjoyed many a post conference beer talking about social media, online travel and building a customer proposition. Great presenter and interesting bloke.

While Chris' day job is as a boss of an insurance company, at night he and his WorldNomad's fellow founders set up Footprints.org. I first blogged about Footprints here. It is a micro donations system that can be built into a purchase path so that small amounts of money can be collected from a large customer base as part of an unrelated consumer transaction. To date they have raised more than $1mm for 65 projects from 411,000 donations. If you are interested in hearing more check out the below video of Chris presenting at the recent TEDx Phnom Penh conference.

Thursday, February 10, 2011

PhoCusWright 2010 summary video including the BOOT asking Groupon's Rob Solomon a question


Three min video above from the PhoCusWright team with some commentary and summary points from last November's PhoCusWright conference. At the 33 second mark you will see me asking Groupon's Rob Solomon about build or buy for Groupon in Asia.

Wednesday, February 09, 2011

TUI on AsiaRooms and LateRooms for Q4 2010


Mega Euro travel company TUI Group have just published their results for the final calendar quarter of 2010 (PDF here).

Online travel companies AsiaRooms and LateRooms make up part of TUI's A&D Sector (for more background on this group see this post on the 2009 performance, this post on the first re-org that combined AsiaRooms and LateRooms and this post on the operational internal merger of AsiaRooms and LateRooms). Here is an extract from the earning release (note where they say Q1 it refers to calendar Q4)

"The A&D Sector reported an improved underlying operating profit of £4m (Q1 10 £1m), driven by a strong increase in roomnights in our accommodation businesses. Our accommodation wholesalers, Bedsonline and Hotelbeds, delivered a 20% increase in roomnights following continued expansion in Latin America, with particularly strong growth in Brazil. LateRooms.com, our accommodation OTA, increased roomnights by 19% as it continued to increase its market share. The increase in profits was partially offset by marketing and product investment in AsiaRooms.com, where we are increasing our hotel content and translating our website into local languages to address the high growth domestic
markets in Asia."
Accoumpianying spreasheet shows that the revenue for sector increased 7% from £121mm to £130mm.

TripIt/Concur Sessions - talking the TripIt acquistion with Concur's Michael Eberhardt

On Jan 13 this year it was announced that travel and expense management company Concur (Nasdaq: CNQR) would pay up to $120 million for the indispensable travel tool Tripit (Kevin May Tnooz story here and press release here). I had a chance to speak last week with Michael Eberhard, Concur's EVP and GM Asia Pacific (pictured) about Concur, the deal and their combined plans for Asia. Three themes from the discussion

1. Asia is a big priority for Concur and TripIt. They are planning to spend a lot of time and money targeting customers in this region;

2. There will be stronger links to travel booking in TripIt. Concur are a large travel management company and are looking to bring that to TripIt; and

3. The social media parts of TripIt are here to stay. I expressed some doubts about the usage of the social media features but Concur remain convinced that these are important features that will be worked on and pushed.

Full interview notes below.

The BOOT Asks:
What are your plans for TripIt post acquisition?

Eberhard: The main goals of the acquisition was to increase investment into all of the TripIt solutions (free, pro product and core business product). Helps [Concur further target] unmanaged biz travel especially those still craving data at deeper level than an itinerary.

The BOOT Asks: I use TripIt extensively for travel planning and co-ordination, but I have not found the social media parts (finding who is in what location) that useful or result in any connections while on a trip. Do you see value in the social media elements of TripIt?

Eberhard: We see the social media parts as important. Personally, prior to the acquisition I made a connections with friends, including one running a marathon in Asia. Combined with mobile and groups will give friends, family and travel managers information and visibility they have not had before.

The BOOT Asks: What are your non-English and Asian plans?

Eberhard: Concur had a lot a success across Asia with existing customers. We are now moving into AsiaPacific to acquire and service customers locally. We will increase staff in Hong Kong and Singapore and through our joint venture in Japan.

The BOOT Asks: Why did you launch a joint venture in Japan and what is the biggest thing about the Japanese market that surprised you?

Eberhard: some of our largest customers have travellers and employees using Concur inside Japan but we have not been acquiring new customers. To address this properly it made sense to do a JV with a local company (press release here).

The number one surprise about the Japanese travel market is that the market is more fragmented than we expected and processes are unique.

The BOOT Asks: Concur is (in part) in the expense management business. What is the weirdest expense you have seen an employee try to charge?

Eberhard: Most companies have some level of fraud. We have examples of lavish parties, including weddings being charged by employees.

My Take

I use TripIt religiously to help me cover 200,000 miles a year in travel. It is always a challenge to see how a start up will fare inside a multi-billion dollar company. Concur seems like a better home for TripIt than a media company or OTA due to the focus on travel and expense management rather than a retail or media model. As I tweeted when the deal was announced - this the first deal of 2011. Is also the first of my list of seven do-overs/reboots (Triporati, Tripit, NewTravelCo/Travelpost, Getaroom, Voyij, Wego and Hotelscombined) to get bought out.

Concur background

I have to admit upfront that I had not heard of Concur prior to this deal. If you are like me in this regard, let me share with you some of the background provided by Eberhard. At the core the company is a "provider of travel and expense management solutions". Market cap is around $2.7b (as of today). They claim 15 million users in 90 countries including big companies like Unisys, Ericsson, JCPenny and Cable & Wireless.

Tuesday, February 08, 2011

The BOOT's Frequent Flyer Gold Rush

After 10 years as a Qantas top tier Platinum Frequent Flyer, I failed to re-qualify. Yet in a twist of frequent flyer magic, just as I was losing top status on QF, through a series of status matches and promotions I managed to get Gold on both Velocity (Virgin Blue) and United. I have also been a Gold Singapore member for a number of years. Making 2011 the first year I have been Gold on four airlines at once. I am sure it wont last into 2012 as even with my travelling load, keeping four in Gold is impossible. But I thought I'd share with you (minus the numbers), the river of frequent flyer gold now available to the BOOT.

My Qantas status is an interesting one. I cannot begrudge Qantas from downgrading me as I failed to accumulate the requisite status credits. In the end I accumulated 1,060 against a target of 1,200 (about 10% short). I called and asked Qantas to do me a favour and keep me platinum (quoting ten years) but the answer was a very polite no. But there is a twist here for Qantas. After years of flying with them I am lifetime Gold (you can see the "Lifetime Member" message bottom right of my Qantas card). Therefore with Gold a lifetime status and Platinum unlikely to be regained in 2011 (re-qualification rises to 1,400 status credits), my incentive to fly Qantas to accumulate status credits drops to zero. If I can't get to Platinum and there is not need to fly to stay at Gold, then it is better for me to push as much as I can to retain my other cards. It is strange how incentives work. By missing out (just) on re-qualifying for Platinum, Qantas and oneworld will likely see a dramatic drop off in my flying and United/Singapore/Star will see a dramatic increase in my travel (prices being equal of course).

Qantas were very polite and charming in my downgrade. In fact they sent me a very well designed white with grey markings pack with my lifetime Gold announcing "Introducing a new way to fly" (photo below)


In addition to the new card and the usual "thank you and here you the list of things you get" note from the CEO and head of loyalty, the pack has two RFID chip based luggage tags. The new card also has an RFID chip. Between the two I can check in (for domestic) and drop off my bags without having to go to a kiosk or visit and agent. Assuming it works it means no more boarding cards or luggage tags (domestic only). More photos of the pack and baggage tag below.